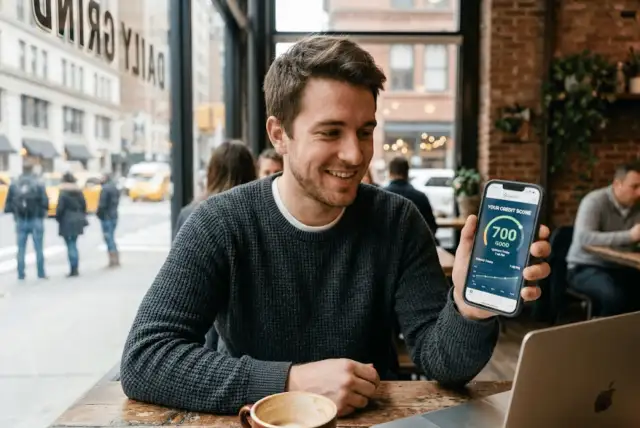
A 700 credit score is generally considered a good credit score, and it can help you qualify for many credit cards, auto loans, personal loans, and mortgages with competitive terms.
However, a score of 700 does not guarantee approval or the lowest interest rates. Lenders also consider your income, existing debt, payment history, and other financial information.
So, if your score has finally reached 700, that is worth celebrating. You have built a solid credit profile. Better yet, there are still opportunities to improve it and potentially save money when borrowing.
Is a 700 credit score good?
Yes, a 700 credit score is good for many borrowers. Most commonly used credit scoring models operate on a scale from 300 to 850, although the way scores are classified varies by model.
For example, a 700 falls within the Prime range under VantageScore. It also signals a relatively healthy credit profile to many lenders.
There is an important detail, though: you do not have just one credit score. Scores can vary depending on the scoring model, credit bureau, information available in your credit report, and when the score was calculated.
That is why the number you see through a banking app may differ from the score a lender sees when you apply for financing.
What can you get with a 700 credit score?
Reaching 700 can expand your borrowing options. You may have access to more competitive financial products than someone with a lower score.
Still, credit approval is never based on the score alone. Here is how 700 may affect some common financial decisions.
Credit cards
With a 700 credit score, you may qualify for a wider selection of credit cards, including products offering cash back, travel rewards, welcome bonuses, or other benefits.
Major issuers such as Chase, American Express, Capital One, Citi, and Bank of America offer cards aimed at consumers with different credit profiles. However, each issuer has its own approval criteria.
Before applying, compare annual fees, APRs, rewards, and other terms. A flashy welcome bonus is less valuable if the card does not fit your spending habits.
Auto and personal loans
A 700 score can also put you in a stronger position when shopping for an auto loan or personal loan.
Banks, credit unions, and online lenders may consider your score when setting your interest rate. However, they can also look at your income, current debts, loan amount, and repayment history.
Therefore, compare multiple offers before signing. Even a seemingly small difference in APR can affect how much interest you pay over the life of a loan.
Mortgages
A 700 credit score can provide access to several mortgage options. However, having a 700 score does not automatically unlock the lowest mortgage rate.
Mortgage lenders look at the bigger financial picture. Your income, debt-to-income ratio, down payment, assets, credit history, and type of mortgage can all influence approval and pricing.
Companies and lenders such as Rocket Mortgage, Wells Fargo, Chase, and Bank of America may also use different underwriting standards. Comparing lenders can help you find terms that better match your situation.
Why a 700 credit score doesn’t guarantee the best rates
Think of your credit score as one piece of a larger financial puzzle.
A lender wants to understand how likely you are to repay the money you borrow. Your score helps answer that question, but lenders may also review your income, debt-to-income ratio, payment history, assets, and requested loan amount.
Another important point is that lenders may not see exactly the same score you see.
FICO and VantageScore offer different scoring models. Meanwhile, credit information can come from Experian, Equifax, or TransUnion. Differences between reports and scoring models can produce different numbers.
As a result, 700 is a strong starting point, but it is not a universal ticket to every lender’s best offer.
How to improve a 700 credit score
Already at 700? Your next goal might be 720, 750, or even higher.
Fortunately, improving your credit does not require complicated tricks. Consistent financial habits usually matter much more.
Never miss a payment
Payment history accounts for about 35% of a typical FICO Score calculation, making it a major factor in your credit profile.
Pay credit cards, loans, and other reported accounts on time. If remembering due dates is difficult, consider setting up autopay or payment reminders.
A long record of on-time payments can help demonstrate that you manage debt responsibly.
Keep your credit utilization low
Credit utilization compares your revolving credit balances with your available credit limits.
For example, carrying high credit card balances relative to your total limits may hurt your credit profile. Paying balances down can reduce utilization and may help your score.
You may have heard that utilization always needs to stay below 30%. However, 30% is not a magic cutoff. Generally, lower utilization is better, as long as you continue using credit responsibly.
Be strategic about new credit
Applying for several new credit accounts within a short period can work against you.
A credit application may generate a hard inquiry. New accounts can also reduce the average age of your credit history.
Instead, apply when a new credit card or loan has a clear purpose. At Unum, we encourage readers to compare costs and benefits first rather than treating every attractive offer as a reason to submit another application.
Let your credit history age
Time can become one of your allies.
The length of your credit history accounts for about 15% of a typical FICO Score calculation. Older accounts and a longer record of responsible borrowing can strengthen your overall profile.
Credit mix matters too, but there is no reason to take out an unnecessary personal loan or auto loan simply to diversify your accounts. Good credit should help you save money, not encourage you to create debt you do not need.
How long does it take to go from 700 to 750?
There is no universal timeline for moving from a 700 credit score to 750.
The answer depends on what is holding your score back. If high credit card utilization is the main issue, paying balances down and waiting for updated balances to be reported could produce changes relatively quickly.
Late payments are different. Building a stronger record after negative information can take considerably longer.
Your credit profile is unique, so be cautious with anyone promising to add 50 points to your score within a specific number of days.
Consistency is usually the better strategy.
Make your 700 credit score work harder for you
A 700 credit score is already a valuable financial asset, but the number itself is only part of the story.
Use your stronger position to compare credit cards, loan APRs, mortgage offers, fees, and repayment terms before borrowing. Meanwhile, keep paying bills on time, manage credit card balances carefully, and avoid unnecessary applications.
Most importantly, do not take on extra debt simply because you want a higher number.
A good credit score should make your financial life easier and potentially cheaper. Keep following Unum to understand credit, compare financial choices, and make your money work smarter.
Frequently asked questions about a 700 credit score
1. Is 700 a good credit score?
Yes. A 700 credit score generally represents a healthy credit profile and may help you qualify for competitive credit cards and loans. However, classifications vary depending on the scoring model.
2. Can I buy a house with a 700 credit score?
Potentially, yes. A 700 score can meet the credit requirements for many mortgage options. Approval will also depend on factors such as income, debt-to-income ratio, down payment, and the lender’s requirements.
3. Can I get a car loan with a 700 credit score?
Yes, a 700 score can make you eligible for many auto loan offers. Your final APR can still depend on the lender, vehicle, income, loan term, down payment, and other factors.
4. Can I get a credit card with a 700 credit score?
A 700 score can provide access to many credit cards, including some rewards cards. Still, issuers consider additional information, so approval is never guaranteed based on score alone.
5. How can I raise my credit score from 700 to 750?
Focus on paying every account on time, keeping credit utilization low, limiting unnecessary credit applications, and maintaining older accounts when they continue to make financial sense.
6. How long does it take to go from a 700 to 750 credit score?
There is no fixed timeline. It depends on your credit history and what is currently affecting your score. Some changes may appear relatively quickly, while recovering from negative information can take much longer.